DEATH OF CLARITY
Floor voting is an arcane & archaic act
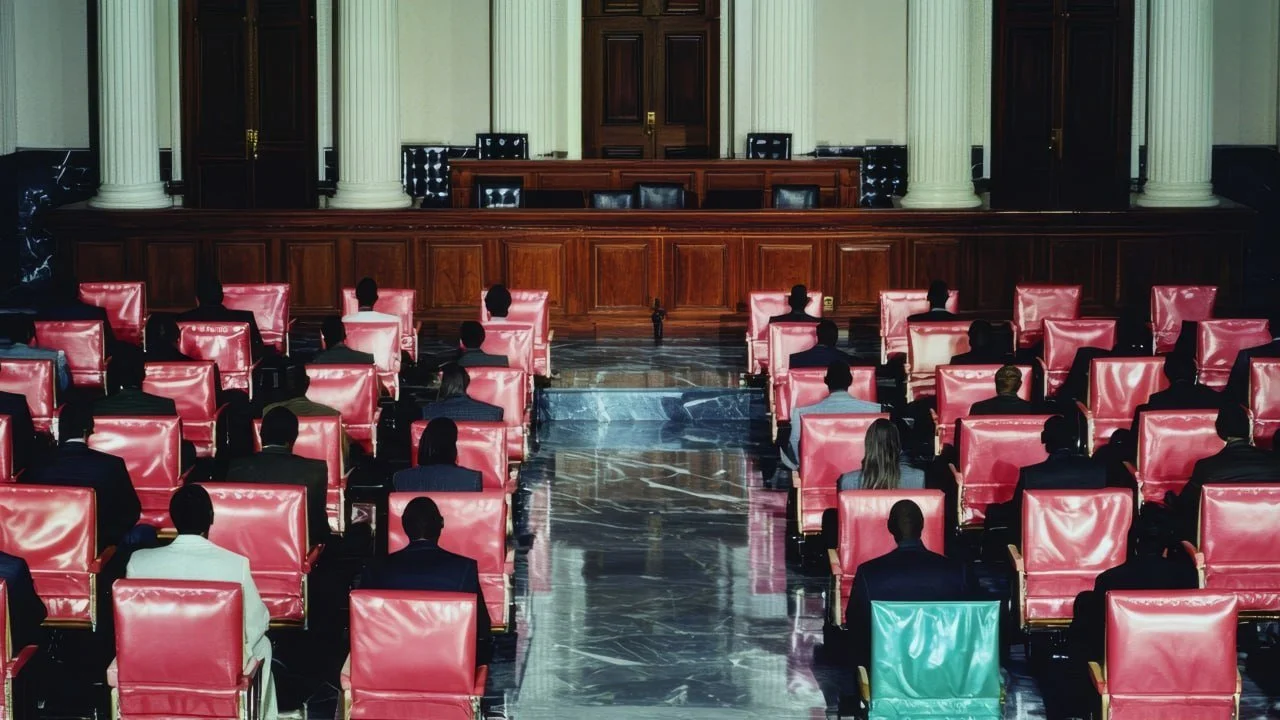
The desks curve around the chamber in rows of polished mahogany. They still have inkwells. Yes, Inkwells!
Microphones are a more recent addition, retrofitted to furniture built for an earlier version of the country, with different borders and fewer senators. And more ink.
The Senate is an institution that grows by putting new equipment into old wood. But even in the 21st century, as microphones themselves are superseded by digital signals, the members have to bring their flesh into the room.
SUBSCRIBE TO ZERO IN
Names are called. Votes are given, recorded, sometimes changed mid-count. On C-SPAN, the procession is measured in minutes, not milliseconds; an insult to the era of flash boys and high-frequency trading. There are faster ways to ask a hundred people a question. The pace is a feature, not a bug.
Then they count. In this case, for Clarity — or the Digital Asset Market Clarity Act — may it rest in peace.
Sixty votes were needed to approve a further vote, but, like former U.S. President James Garfield, they only made it to 49. Tillis flipped to no for arcane procedural reasons that will be misinterpreted.
According to the official description, this was a failure to invoke cloture on the motion to proceed. A linguistic monument to procedure, for a room where a vote about having a debate about having another debate can be a matter of life and death.
Outside, the translation is simpler:
Clarity is dead. For now. Possibly for quite a while.
The desks will be here for the next try, in a year or two or fifty. They’ll probably still have the inkwells.
Information Compression
What the camera cannot show is everything arriving in the room with each senator with loads of intellectual and metaphorical baggage. Each senator bears a thousand invisible gifts to the process.
Deliveries come on behalf of donors; employers back home; primary challengers; and party leaders. Constituents who want ten incompatible things, pitted against a lobbyist with proposed language, a staffer responsible for the actual words that make up the bill. Typos, missing sections, presidents, elections. They’re all voting, too.
You can’t see all these forces in tension; you just see the final yes or no, compressing an entire little ecosystem of obligation, ambition, belief, and self-preservation into a single binary bit — the smallest unit of information possible.
The Senate appears to prefer it that way.
But to understand the failure, we have to work backward from those floating, visible bits. We have the text, the public arguments, the demands, the concessions, and the vote: the wreckage left behind by a ship’s catastrophic foundering.
So here’s my read:
Clarity tried to finish too many fights at once. That can work when there’s a supporting coalition for the package, strong enough to overcome the people who hate pieces of it. It can also work when someone with a bully pulpit whips a coalition into shape.
Instead, the disagreements inside and around crypto kept multiplying and sowing division instead of unity. Securities classification. Trading rules. Software liability. Bank funding. Presidential ethics. They all had different constituencies and some with very few shared interests.
It was the legislative equivalent of making a pizza with beets, grapefruit, Brussels sprouts, blue cheese, anchovies, and pineapple. There are people who like each of these things. Finding someone who wants to eat them all at once is tougher.
Clarity did not find sixty of them.
What It Was
Every bill is stitched together from language from staffers, lobbyists, advisers, and the remains of earlier bills. Clarity was a particularly ambitious stitching project.
It would have divided responsibilities between the SEC and CFTC; created offering and disclosure rules; registered trading intermediaries; addressed custody and bankruptcy; and added anti-money-laundering obligations for those intermediaries. Self-custody protections and restrictions on a retail central bank digital currency were in there too.
A lot of this was necessary work – there were useful things trapped in the package.
But three fights pulled the seams apart.
Yield
The banking lobby warned that stablecoins would pull trillions of dollars out of bank deposits and deprive businesses and households of credit. The ABA’s Community Bankers Council put $6.6 trillion of deposits at risk in its letter to the Senate, citing the Treasury in a report written for them by the same bankers now citing the report.
It’s a nice scary number. But let’s follow a dollar.
A customer buys a stablecoin. The customer’s bank deposit becomes the issuer’s bank deposit. The issuer buys a Treasury bill from a nonbank seller. The issuer’s bank deposit becomes the seller’s bank deposit.
The deposit is still there, guys.
It moved. But it didn’t disappear into the blockchain. It wasn’t eaten by a smart contract. It didn’t fall into a hole in the internet.
If a bank sells a Treasury from its own balance sheet and extinguishes a deposit in the process, that is the bank choosing to sell an asset. The stablecoin did not compel the sale. Treasury issuing debt and later spending the proceeds involves Treasury’s decisions. Neither is evidence that creating a stablecoin itself destroys bank deposits.
“You made me do this,” the banker screams, voluntarily selling a Treasury at a price the banker has agreed to accept.
No. You sold a Treasury.
The disappearing-deposit story was engineered to spook policymakers and hamstring competition. The banking lobby either genuinely misunderstands the accounting behind its own warning – or it is presenting an argument the accounting does not support.
The bankers are either lying deliberately, or don’t understand their own business.
Crypto’s mistake was to accept that premise, then argue for permission to build a business on it. Once the discussion becomes how much deposit flight should be tolerated in return for stablecoin rewards, the banking lobby has already won (dishonestly). Crypto was not sophisticated enough to challenge the premise, once again showing how immature the industry is with regard to interactions with regulated finance.
Meanwhile, asset managers were silent, letting banks and crypto fight - to their benefit because you can always pay yield on a money market fund. You can also use them as reserves for a stablecoin. You could have a stablecoin that automatically converts to the fund to pay yield if you know the customer. Who can do that easily? Asset managers. Now you know why they stayed out of it.
The final Clarity proposal nevertheless carried both yield restrictions and a Treasury circuit-breaker aimed at community-bank deposit outflows. That’s even more egregious, because it’s a problem that predates stablecoins: community banks have shrunk from nearly half the market in the US to under 20% from 2009-present, representing trillions of dollars of flows against $300B of stablecoins, which really only took off after 2020.
The market structure bill was given a second job: refereeing the incumbents’ fight over who gets to rip off the customer, with all sides blaming the new guy for getting involved … and not trying to rip off the customer.
BRCA
The next fight is about whether writing software can put you in prison.
More precisely, when does providing software become operating a money-transmitting business? At what point does the person who builds the tool become responsible for the money someone else moves with it?
This is the question the Blockchain Regulatory Certainty Act (which really should have a better acronym than the gene that causes breast cancer, as an aside) was supposed to help answer. The word “certainty” was doing useful work there.
FinCEN’s guidance distinguishes providing software from providing a money-transmission service. It discusses control, different wallet arrangements, and the circumstances in which a business accepts and transmits value. An engineer trying to understand the rules could reasonably start by reading what the federal financial-crime regulator says.
Then comes the Justice Department.
In the Tornado Cash prosecution, DOJ expressly argued that Section 1960 does not require control over the funds. It argued that FinCEN’s guidance did not establish such a requirement, was not binding, and did not determine the reach of every branch of the criminal statute.
Read the guidance. Build your understanding.
And then you get a fun surprise: the prosecution has quite a different framework.
Storm was convicted of conspiring to operate a money-transmitting business involving criminal proceeds. DOJ alleged the operation of a service and knowledge of criminal activity, not merely the existence of some published code. That might make Storm’s conviction more legitimate, but it leaves no clean test for deciding where software ends, and money transmission begins.
Take a browser. Add a wallet. Add email, where people can privately arrange transactions, and access to a bank’s website, where they can execute them. There is a commercial business behind all of this. It earns money. Some of its users will be criminals.
Where, exactly, is the line? Is Google a money transmitter? Is Brave? Is Microsoft? Is your ISP?
There is a regulatory exclusion for providing only communication or network-access services. But the DOJ itself argued that this exclusion does not govern every branch of Section 1960. So are you a money transmitter or not? Try it and find out!
It’s a bit like having to buy a house to find out what’s inside of it.
I want actual financial crime prosecuted. I also want the government to explain what makes someone responsible for a transaction before trying to enforce that responsibility. More prosecutorial reach is not automatically better enforcement, especially if it makes ordinary infrastructure legally hazardous while doing little to stop the people stealing the money, doubly so if it accelerates the KYC data-honeypot creation that has been such a godsend to hackers, scammers, and thieves.
On the other hand, wanting a clear line does not make every advocate a saint. A serious lawyer may want predictable rules. A developer may want to ship a useful product. Someone running a dubious business may want the broadest possible shelter from scrutiny. They can all support the same sentence. The specific language matters more than which camp is cheering.
The final BRCA language protected specified non-controlling developer activities from registration requirements while preserving treatment under other laws for conduct outside its scope. But the DOJ never defined that scope in practice, and simply denied any exemptions applied. There was still an unclear relationship between exemptions and criminal money-transmission liability.
A line can be debated. Moved. Written narrowly or broadly, within reason. What it cannot usefully be is something that becomes visible only after a prosecutor decides you crossed it.
This is a fight that was genuinely lost after it was delegated to Clarity. I understand why many crypto advocates turned against the bill on that basis.
Ethics
Donald Trump towers over the media landscape, his comb-over profile casting a shadow even when his name is unspoken. Naturally, he was at the center of the Clarity fight.
The proposed ethics rules covered federal officials and spouses. They restricted compensated digital-asset issuance and sponsorship, and certain financial interests, with divestiture or a qualified blind trust among the available paths.
That sounds like the outline of a rule. But enforcement remained questionable.
For alleged violations by officials, state attorneys general could act against the US Attorney General, with a special court procedure. The Office of Government Ethics could rule that an issuance or sponsorship was permitted, stopping that route. And guess what: the director of the Office of Government Ethics is appointed by the President.
So the proposed outside check retained an inside switch: The executive branch could shut the state enforcement route off. That boils down to the President policing the President.
It’s easy to understand both why that is a bad system and why the Democrats, rightfully in our view, rejected it.
Then there is the underlying business. Trump’s family has been selling crypto products while his administration shapes the rules for crypto. The presidency and the product promotion occupy the same public field of vision. Calling the resulting conflict concern imaginary means you’re not actually looking at it.
But the reverse question also exists: why would the principle stop at crypto?
Who Checks Congress?
If elected or federal officials should not profit from powers entrusted to them by the public, then it should not apply only to one branch.
The question reaches congressional stock trading, household portfolios, disclosures, enforcement, and the financial activities of Presidents who have never heard of a seed phrase. Nancy Pelosi’s portfolio is just as much of an issue as a Trump-branded token. The conduct need not be identical for the rules to need a consistent explanation.
A disclosure is not proof of a crime. But it doesn’t remove conflict of interest, either. It doesn’t tell us why they bought it: Perhaps based on information not available to the public? Right now, insider trading by Congress is essentially legal.
They’re mad at Trump for doing it better.
There have been bipartisan efforts to address congressional trading. Gillibrand and Moody are among the people doing that work. Clarity, however, did not become a comprehensive settlement of those questions. It carried a crypto-specific ethics package into a much larger and older dispute.
That is a different class of concern; ethics is a meta-legislative issue, not one inside the four walls of the bill.
Here’s what I mean: Yield concerns the economics of a product. BRCA concerns the boundary of a defined legal activity. Both matter beyond crypto, but each presents a problem that can at least be framed and negotiated on its own terms.
The ethics fight, by contrast, asks whether the people making and administering all these rules can be trusted with the power they are giving themselves, and if they are doing that fairly on each side. The answer, so far, is no. Across the aisle, across the entire board.
Trump’s critics have a real conflict to point at. The presidency is being used alongside a family crypto business in ways that deserve scrutiny. Trump, in turn, has a legitimate general objection available: Congress should not design standards for presidential financial conduct while leaving its own unresolved conflicts outside the frame.
The local political questions are one thing. However, the entire debate around ethics and the politically motivated talking points on both sides should leave all Americans asking this about Republicans and Democrats: do we trust them to police themselves?
Judging by the arrangement they were willing to accept from one another: absolutely fucking not.
Confusion, Not Conspiracy
There is a temptation to look at this mess and assume someone designed it.
A hidden hand. A coherent “they.” Someone who understood all the moving parts and arranged the outcome.
Let me be the first to tell you: No.
This is the kind of story with no simple, satisfying explanation. Just the complexities of human frailty in their emergent interplay.
There were coordinated efforts inside this process, of course. Lobbying, party strategy, industry pleading for special protection. All of those groups had internal cohesion (some more than others). But coordination within a faction does not mean control over the whole system. A room full of people each trying to get their own way can produce an outcome that almost none of them wanted. That’s what happened here.
The Democrats have crypto mad at them. The Republicans made Trump a target in the election and covered themselves in a mess. Law enforcement now looks like they are trying to shut down the internet. The banks look like they are trying to fuck their own customers. Crypto looks like they got played. Developers, at least, came out of this no worse than their already dicey situation.
It’s more like Idiocracy than a conspiracy.
Enough low cunning, local calculation, technical ignorance, commercial self-interest, and institutional mistrust to produce a collective failure. No grand strategist required.
None of us, you see, is as dumb as all of us.
What Comes Next
Start by accepting the failure we actually have.
Crypto did not get durable market rules. The package did not produce the coalition its supporters needed. Calling everyone who voted no an enemy of innovation will not tell us which parts could have passed, which objections were substantive, or which concessions made the next objection worse. It also revealed that the groundswell of public support for crypto just isn’t there.
Crypto needs a new strategy: break things apart, find allies on specific causes, and assemble the ship one plank at a time, not trying to carve the whole thing out of one tree. Coalition building is needed for durable success.
On software developer liability, people far beyond the cryptosphere need a predictable boundary, too: crypto isn’t the only direction from which software is eating money! On custody and market rules, the people who benefit include customers who don’t care which industry gets credit. On payments and savings, the objective should be a better deal for the user, not preservation of any particular company’s margin.
Find those allies. Give them something worth supporting. A coalition requires shared interests, not matching profile pictures of NFT collections. Nobody cares about your dickbutt (sorry, Christian).
If the larger ethics dispute is the blocker, confront it as a larger ethics dispute. Congressional trading, presidential businesses, spouses, disclosures, and credible enforcement belong in that discussion together. Bring people from both parties who are willing to accept rules that apply when either side holds power. Use the Super PACs to push for it in a bipartisan way, and target elected officials who want to keep the grift going. If that problem is upstream of Clarity, force them to confront it.
That’ll be tough. So was spending all this time assembling a bill that could not clear its first floor hurdle.
The lesson for crypto cannot be to become more completely attached to one president, one party, or one approach. Becoming Trump supporters is not a substitute for building a legislative coalition. Build support that can survive him. And the next person. And the one after that.
Go back to the text. Separate the fights. Find the people outside the tribe who need the same things to work. That would require crypto to accept that people outside this one industry might have not just shared priorities, but shared dignity and value.
That’s how you find the votes.